I had a salary.
What I wanted was freedom.
I was earning roughly $80,000 a year in Los Angeles, and living in a tiny converted garage just to keep my costs down.
After taxes, I took home about $4,800 a month. Ordinary living expenses consumed nearly everything. I had a professional job, but I still felt dependent on the next paycheck. Earning a respectable salary had not given me the freedom I expected. I wanted to change the financial structure of my life.
A fellow Army Reserve soldier introduced me to an idea: buy a small apartment building, live in one unit, and rent the others.
What is house hacking, and how does a fourplex fit?
HOUSE HACKING
You buy a property, live in part of it, and use rent from the rest to help pay for your housing. In a fourplex, that can mean living in one apartment and renting the other three.
If you are looking for your first home, a small multifamily property is another option to evaluate. You gain a place to live and potential rental income, along with the costs and responsibilities of being a landlord. The question is whether that combination works for your life and your numbers.
Three advantages worth understanding.
A different down-payment equation.
Eligible owner-occupants may have access to lower-down-payment options than buyers of a comparable investment property. Eligibility, reserves, insurance, and closing costs still matter.
Qualifying rent can change the picture.
Depending on the loan and underwriting, qualifying rent from other units may count toward income. A lender will not necessarily count every dollar of advertised rent.
Ownership and rental income can work together.
Owner-occupied financing and rent from neighboring units may reduce your personal housing burden. Better terms or a lower rate are not guaranteed.
The lesson: price alone does not tell you what housing costs.A more expensive building with rental income can have different monthly economics from a cheaper house. You have to run the full numbers.
The search nearly broke
my confidence.
My early approach was simple: find the cheapest building and get my payment as low as possible. That kept sending me toward deals that looked better on a listing than they did under closer examination.
By around Property 20, I was looking at the relationship between rents, financing, condition, location, and future options. By Month 12, I was exhausted. Quitting felt reasonable.
Then a fourplex appeared with an asking price of $650,000. My offer was accepted at $610,000. After so many rejections, I finally had a property under contract.
My fourplex house-hacking numbers.
Three apartments were occupied. The fourth, the one I would live in, was vacant. The relationship between the rent and the payment caught my attention.
Three occupied units
As reported at purchase
Rent minus the reported mortgage payment: about $42/month, before other costs. That narrow difference is why the full expense picture matters. It is not a cash-flow or “living free” calculation.
Maintenance, utilities, vacancy, taxes, insurance, and reserves still mattered. I estimated my personal housing cost at roughly $800 per month while living in a much larger space.
I had traded a small converted garage and rent payments for ownership of an income-producing building. The property was imperfect, but the underlying structure was compelling.
How to analyze a house hack
beyond the mortgage payment.
Here is how to examine the purchase figures above. This is a worked reading of the case, not a reconstruction of every original underwriting assumption.
WHAT YOU SEE$3,742 in rent versus a ~$3,700 mortgage.
WHAT TO CHECK NEXTWhat does the payment include? Add every cost outside it before calling the difference cash flow.
A vacant fourth unit you can occupy.
What will your total housing cost be? Do not count rent from your own unit while you live there.
Potential appreciation and future expansion.
Can you afford to hold the property if that upside takes longer, or never happens?
Try this on your next listing: write down one assumption that could make the deal fail, then identify the evidence you need before making an offer.
What the fourplex earned in 2015.
By 2015, I was living in Germany for work. A property manager handled rent collection, routine repairs, and day-to-day operations. I reviewed reports and made decisions that required owner approval.
One operating statement gave me a clearer picture of what I had built.
| Rent collected | $75,735.63 |
|---|---|
| Expenses processed by manager | ($6,976.58) |
| Property taxes | ($8,135) |
| Insurance | ($2,037) |
| Adjusted net operating income | ~$58,587 |
| Mortgage principal & interest | (~$34,372) |
| Amount after principal & interest | ~$24,215 |
About $2,018/month before reserves and income taxes. Tax and insurance escrow are not counted again in principal and interest. A historical case-study snapshot, not a typical or guaranteed result.
The statement showed that the rental operation could support the property while I was thousands of miles away. Reliable records and a repeatable management system mattered.
My first instinct was to sell.
I chose to hold.
While I was in Germany, an income-based estimate approached $950,000 around Year 3 and exceeded $1 million by Year 4 as rents changed. An online estimate also crossed that threshold around that period.
Those were estimates, not sale prices. But after taking about five years to save $22,000, seeing substantial estimated equity felt extraordinary.
The longer I studied what I owned, the more I realized selling was not my only option.
“What holding gave me was not a guaranteed return. It gave me options.”
From four units
to a new set of possibilities.
More than a decade later, I estimated the property’s pre-project value at approximately $1.7 million. The next idea: replace the garage area with two new accessory dwelling units.
This involves new construction, approvals, infrastructure, and an estimated construction budget of roughly $350,000.
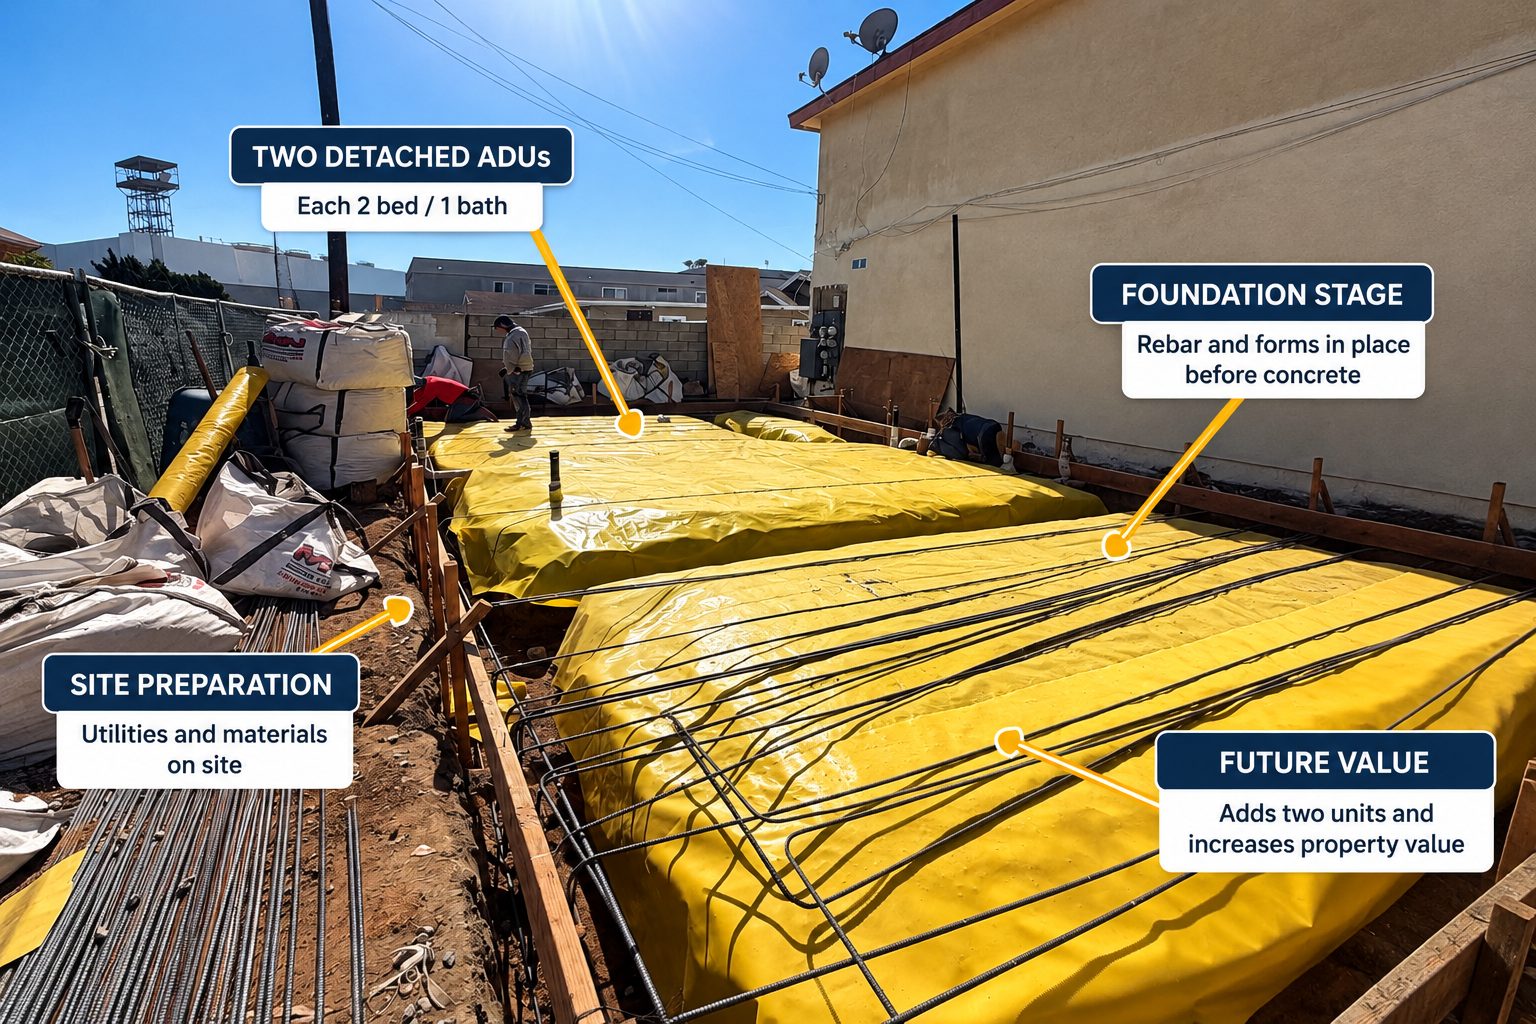
If completed, leased, and operating as modeled, the planning scenario assumes about $125,000 in annual stabilized net operating income.
Where the ~$2.2M figure comes from.
before construction
construction budget
completed & stabilized
Property value is not personal equity. The apparent ~$500K value increase against ~$350K in construction is not realized profit. Costs, financing, delays, final rents, expenses, and capitalization rates can change the result.
The property was the beginning.
The thinking was the real lesson.
Rent helped carry housing costs. Principal payments reduced debt. Operations and market conditions affected value. Holding preserved future options. Each force mattered, and each came with risk.
See the opportunity.
Can I afford the monthly payment?
Understand the advantage.
Can rent from other units help cover that payment?
Evaluate the conditions for success.
What must be true about financing, rents, expenses, reserves, and risk, and what happens if I am wrong?
You do not need my exact property or career path. You need a process that helps you know when to buy, when to keep studying, and when to walk away.
Three questions worth asking.
Does rent covering the mortgage mean I can live for free?
No. Costs outside the payment, repairs, vacancies, and reserves still matter. In my case, I estimated roughly $800 per month in personal housing costs. Compare the full housing cost, not just the mortgage, with your alternatives.
What changes when I move out and rent every unit?
The unit you occupied may generate rent, but the property must also support its operating costs, debt payments, and reserves. Include management if you will use it. My 2015 results are one historical snapshot, not a forecast for another property.
What can an older purchase teach me about buying today?
The prices and financing conditions will differ. The useful lesson is the process: verify rents, identify all costs, test your assumptions, and consider whether you can hold through setbacks. Use current local figures for a property you are evaluating.